Who Should Buy a Critical Illness Cover?
Individuals seeking protection against possible health emergencies can find a comprehensive shield with a critical insurance policy, especially with a medical history or pre-existing diseases. The benefits of critical illness policy coverage are extremely valuable for:
- Individuals with a Family History of an Illness:If a critical condition runs in the family, it also increases the risk for other family members. Thus, it becomes essential for you to take adequate coverage with a critical illness cover policy.
- Breadwinning Family Members:A family's sole breadwinners must consider their family's financial security and get covered with critical illness insurance as early as possible.
- Women: The increasing number of cases of cancer in women is alarming. Thus, investing in a critical care insurance policy is the best advice if you are prone to such risks.
We at Care Insurance provide specialised critical illness benefits. Our easy-to-acquire individual and family health indemnity plan covers 32 critical illnesses pre-defined in the policy.
Features of Critical Illness Health Insurance
Our insurance plan for critical insurance policy contains the following significant features:
- Chemotherapy and Radiotherapy: Care's critical insurance policy covers cancer, underlying chemotherapy, and radiotherapy up to the sum insured so you can feel at ease during therapy sessions.
- Pre and Post-hospitalisation: Ensure financial backup during tests and the recovery phase with 30-day pre- and post-hospitalisation, 60-day coverage.
- Dialysis Coverage: Ensure financial backup for dialysis coverage under specific critical conditions up to the sum insured.
- No Claim Bonus: Celebrate claim-free years as we offer up to a 100% increase in the insurance premium to give you better coverage every year.
- Healthcare Services: To keep up with your health, utilise our value-added services of quick recovery counselling, doctor on call, and digital health portal.
- Ambulance Cover: Get timely medical care without worrying about transportation costs, as we cover ambulance fees up to a specified amount.
Benefits of Critical Illness Insurance
Critical Care Insurance offers substantial economic and emotional backing in case of a serious medical condition. Here are some of its key benefits:
- Comprehensive coverage: You do not have to worry about the unpredictable costs of severe treatments. All eligible medical expenses, including hospitalisation costs, room rent charges, and OPD expenses are covered.
- Strengthening your financial defense: Your regular health insurance covers hospitalisation. Critical Illness Insurance strengthens your protection against the most expensive medical conditions.
- Provides confidence during uncertain health events: Knowing that coverage exists for serious, life-altering conditions allows individuals to focus on treatment decisions, recovery and rehabilitation, and family responsibilities.
- Alternative treatments: Critical illness benefits include covering treatments such as AYUSH.
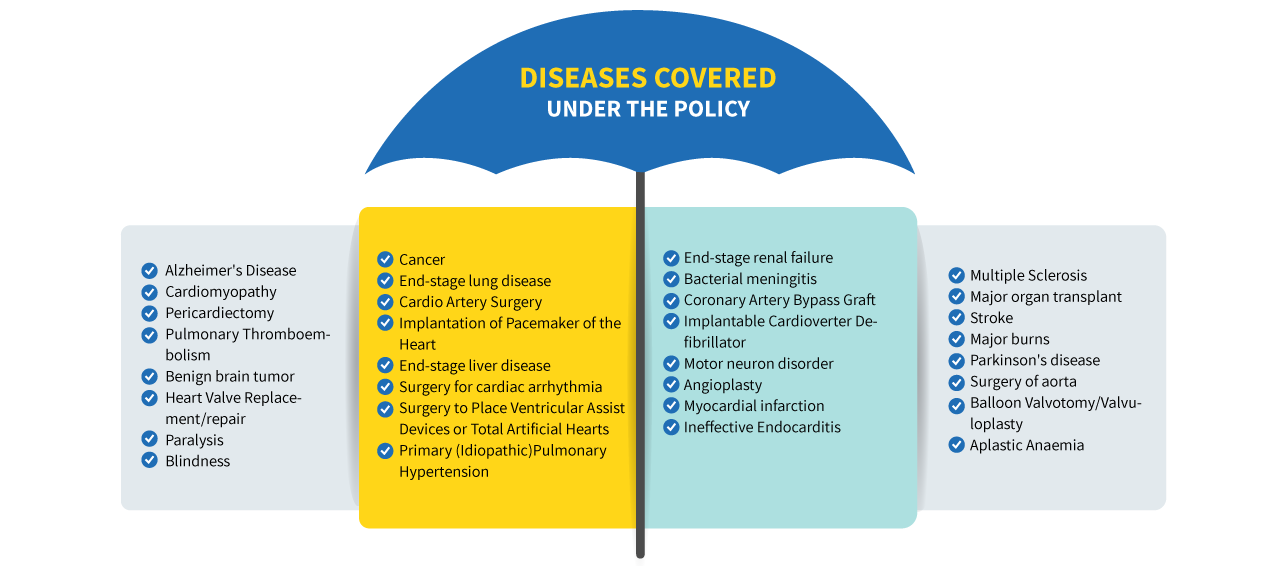
Critical Illness List: Diseases Covered Under the Policy
Critical Care insurance Plan provides coverage for 32 life-threatening medical conditions. Here are the list of the diseases covered in the plan:
Optional Benefits of Critical Insurance Coverage
Optional covers can be included in your policy to provide enhanced support during an emergency. Below are the optional covers you might not want to miss while buying yourself a critical illness cover policy:
Room Rent Modification
Just like care should have no limits, your room rent category/rent should not have any restrictions or limits. This benefit will allow you to stay comfortable in the hospital.
International Second Opinion
A second opinion is always helpful if you are unsatisfied with the first. This plan allows you to take a second opinion globally if needed.
Air Ambulance Cover
Through this benefit, we will cover you up to the amount specified in the covered critical illness policy for availing air ambulance services in India, subject to the terms and conditions of the policy.
Global Coverage
This benefit allows you to claim hospitalisation expenses for the covered conditions incurred outside India up to the sum insured.
Exclusions: Critical Illness Insurance Cover
Sometimes, policyholders are disappointed with their insurance plan because of misinformation about the coverage limits. Hence, it is advisable for policy buyers to carefully review their critical insurance policy’s exclusions to avoid such a situation in the future.
Claims deriving from the following are excluded:
- Act of self-inflicted injury, attempted suicide, or suicide
- Any illness related directly to the consumption of alcohol/ tobacco/cigarettes, etc.
- HIV or any other sexually transmitted disease
- Cosmetic or plastic surgeries or related treatment
- Pregnancy, miscarriage, childbirth, maternity including C-section, abortion, or complications of any of these
- Damage caused by a nuclear, chemical, or biological attack or weapons
- Illness or injuries caused by any breach of law by the insured with any criminal intent
Our plan offers comprehensive critical health insurance that helps policyholders combat essential diseases.
How Does Critical Illness Insurance Work?
Understanding how critical illness they work can help ensure you are ready in case of a diagnosis.
Process from Buying to Claiming Critical Illness Insurance:
- Research and Comparison - Begin by comparing several insurance providers and policies. Choose policies that cover a vast range of critical illnesses like heart attacks, cancer, strokes, kidney failure, etc.
- Purchase the Policy - Choose a plan based on your needs, selecting the coverage amount and term. During the application process, provide proper personal health details.
- Premium Payments - Don't overlook regular premium payments as agreed in the policy. Missing payments may cause policy cancellation or reduced coverage.
- Waiting Period - Most critical illness cover policies have a waiting period before a policyholder can file a claim. The period differs and often lasts 30-90 days.
- Diagnosis of Critical Illness - The policyholder must contact the insurer when diagnosed with a critical illness during the policy term.
- Claim Submission - The policyholder must submit the claim form and supporting medical documents to the insurance provider.
- Claim Assessment - The insurance company assesses the claim to ensure it meets policy conditions. Then the eligible medical expenses are settled upon approval.
How to Select the Best Critical Illness Cover Online?
Like any other insurance policy, you must consider several factors when choosing the best critical illness insurance in India. You must also consider comparing different plans along with the following checklist:
- Check the Coverage - The Sum Insured should be sufficient to reimburse your eligible medical expenses in the event of an illness. This decision can be made based on your savings and other financial options.
- Calculate Premium Rates - Most policy buyers shortlist insurance policies solely based on premium rates, which is understandable. You can use a premium calculator to get the best critical illness insurance plans quote online.
- Ensure Less Waiting Period - Like other health insurance plans, a critical insurance policy includes a waiting period. Care Health Critical Insurance policies come with a standard 90-day initial waiting period and a 36-month waiting period for pre-existing diseases.
- Find Out the Covered Illnesses - Knowing what diseases are covered under the best critical illness insurance plan in India is crucial. Especially if you are purchasing the policy because you have a family history of a medical condition, it is in your best interest to be aware of the coverage provided by the plan.
- Learn About Renewal Policy - These plans usually have an age limit on renewability. Select a plan with a more extended age limit so that it can be renewed at any stage of life without hassle. Also, watch for the claim process and sub-limits for surgery, diagnostic tests, and other procedures.
Eligibility Criteria for Purchasing a Critical Insurance Policy
| Entry Age- Minimum |
Child: 91 days to 4 years with at least I member of age 18 years or above is covered or; 5 years on Individual basis
Adult: 18 Years and above |
| Entry Age- Maximum |
50 years |
| Exit Age |
No Exit Age |
| Age of Proposer (Adult) |
18 Years or above |
| Who are covered (Relationship with Respect to the Proposer) |
Self, legally married spouse, son, daughter, father, mother, brother, sister, mother-in-law, father-in-law, grandmother, grandfather, grandson, granddaughter, uncle, aunt, nephew, niece, employee or any other relationship having an insurable interest. |
How to File a Claim Under a Critical Illness Insurance Plan?
Critical Care insurance ensures a seamless claim process for its customers. Here are the steps to follow while filing a cashless claim or reimbursement for critical illness insurance.
| Cashless Claim Process |
Reimbursement Claim Process |
| Step 1: Go to a listed in-network hospital. |
Step 1: Submit your claim form along with other required documents. |
| Step 2: Fill out the required forms at the insurance desk. |
Step 2: You'll get an approval letter when your claim is verified. |
| Step 3: Send the completed form to our claim management team. |
Step 3: Respond to queries raised by the claim management team. |
| Step 4: You'll get an approval letter when your claim is verified. |
Step 4: Get approval from the claim management team. |
|
Step 5: Respond to queries from the claim management team. You will receive communication about whether your cashless claim is approved or rejected.
|
Step 5: Upon final approval, the reimbursement for eligible medical expenses is processed. You will be contacted if the claim is rejected. |
How Important is Critical Illness Insurance for the Family?
A critical illness diagnosis can be emotionally and financially devastating for an entire family. Care Insurance's critical illness cover acts as an essential financial safety net, protecting your family’s future when they need it most.
The best critical illness policy is advantageous in the following ways:
- Critical insurance policy for coverage is a safety net that protects you significantly, covering 32 critical illnesses.
- Because this indemnity-based plan covers numerous medical expenses you incur throughout the year, a high sum insured provides you with total security.
- You have extensive financial protection for hospitalisation and advanced medical procedures, such as chemotherapy and radiotherapy, which are essential for treatment.
Things to Keep in Mind While Buying a Critical Illness Insurance Policy
Critical illnesses need long-term treatment in most cases. A hurried lifestyle, in addition to inherited factors, might trigger the occurrence of such medical disorders. When buying a critical insurance policy, here are some points you need to keep in mind:
- Budget: If you have enough financial resources to deal with an unforeseen medical problem, you might choose the best critical illness insurance plans with less coverage. However, remember that healthcare expenses are rising at an unprecedented rate, so relying only on savings could cause irreversible financial loss.
- Health Needs: Understand your health needs to get the best critical illness policy in India. Evaluate your current health condition, age, lifestyle habits, and family medical history to identify the likelihood of critical illnesses.
- Inclusions: Each policy comes with its own set of features. Hence, it is crucial to understand what a particular plan offers to align with your needs appropriately.
- Limitations: It's just as vital to know what's not covered by your critical insurance policy. Also, check the policy's waiting period to avoid any rejected claims in the future.
- Claim Process: As a policyholder, it is in your best interest to know about the documentation you must provide and the procedures for filing a claim so you will be ready when the time comes.
- Coverage Size: A standard health insurance policy cannot cover certain treatment costs. So, choose the best critical illness insurance plans in India that covers the treatment of such conditions.
- Claim Settlement Ratio: An insurance provider's claim settlement ratio indicates their ability and intent to settle claims. Hence, consider the claim settlement ratio before buying the best critical illness cover.
How to Buy Critical Illness Insurance Plans Online at Care?
You do not need to go through the cumbersome formalities to buy critical insurance policy online from us. Our buying process is simple; you can follow the below steps to get your critical illness health insurance:
- Visit our website and select a health policy.
- Click on 'Get Quote' and provide relevant details.
- Choose any of our secure digital payment modes to buy the policy.
- You will get the new health policy documents in your registered email.
Documents Required for Critical Illness Insurance Claim
If you want to file a claim, contact us to make a claim registration. To file a claim, you'll usually need the following documents:
| Document Type |
Description |
| Claim Form |
The insurer gives a claim form to complete. |
| Medical Report |
A report from the treating health expert detailing the diagnosis, treatment, and prognosis. |
| Diagnostic Test Reports |
Test results, such as blood tests, scans, or biopsy reports, confirm the critical illness. |
| Discharge Summary |
If hospitalisation occurs, the discharge summary from the hospital facility. |
| Policy Document |
A copy of the critical illness insurance policy that includes coverage details and terms. |
| Identity Proof |
A government-issued ID such as Aadhar card, passport, driver’s license). |
| Address Proof |
Residential bills, utility bills, etc. documents |
| Medical History Documents |
Medical history or reports related to the disease, if applicable. |
Tax Benefits of Critical Illness Insurance Plans in India
Critical illness health insurance premiums are deductible under Section 80D of the Income Tax Act 1961. Below are the tax benefits you can get on the premium you pay for the necessary illness policy according to age:
| Category |
Eligibility |
Tax Deduction Limit |
| Tax Deduction for Self, Spouse, and Children (Under 60) |
For individuals under the age of 60 |
Rs 25,000 per year |
| Tax Deduction for Self, Spouse, and Children (Above 60) |
For individuals over the age of 60 |
Rs 50,000 per year |
| Tax Deduction for Parents (Under 60) |
For parents under the age of 60 |
Rs 25,000 |
| Tax Deduction for Parents (Above 60) |
For parents over the age of 60 |
Rs 75,000 |
| Total Deduction for Family Premium (Under 60) |
For individuals paying premiums for their family (under 60) |
Up to Rs 75,000 |
| Total Deduction for Family Premium (Over 60) |
For individuals over 60 paying premiums for their family |
Up to Rs 1,00,000 |
How is Critical Illness Cover Different from Health Insurance?
Often, people get confused between a standard health insurance plan and a critical illness insurance policy. Not only that, but some of us believe that one of the two is sufficient in terms of health insurance.
Know how health insurance and critical illness insurance are vastly different from each other:
| Factors |
Critical Illness Insurance |
Health Insurance |
| Coverage |
It covers hospitalisation due to life-threatening critical illnesses. |
It covers standard hospitalisation conditions and treatment expenses. |
| Benefits |
Pre-and post-hospitalisation, organ donor cover, dialysis cover, psychiatric counseling, etc. |
In-patient hospitalisation, pre and post-hospitalisation, daycare treatments, ICU charges, and more. |
| A number of illnesses |
32 critical illnesses |
Different types of chronic diseases, medical treatments, and procedures. |
| Waiting Period |
90 days initial waiting period (36 months for pre-existing diseases) |
30 days initial waiting period (36 months for pre-existing diseases). |
| Policy Period |
Long-term Policy |
Annual or Long-term Policy |